
2026-02-18 07:40:00


GLOBAL MARKETS(2026) : RESPITE PROVISION
Peeling off the years data like concentric skins of an onion,we find a cornucopia of eventful activities within the global markets sphere.Kicking us off is metals portfolio whereby January had javelins been thrown all over the place.After precious metals dramatically outperformed stocks last year, investors are signalling in chatters of currency debasement with gold outperforming the S&P 500 MTD & YTD.On the Silver porrfolio,sharp rises and deadcats bouncing has been part of the playbook as COMEX Silver inventory gets lower & lower by the day even with March delivery contracts rolling over to later months.Also,looking into intolerance perception is Mexico, point in case being the safety of mining activities in the jurisdiction(Vizla Silver mine) amidst further supply constraints.
Movement in Gold prices will be the confirmation of the macro narrative.
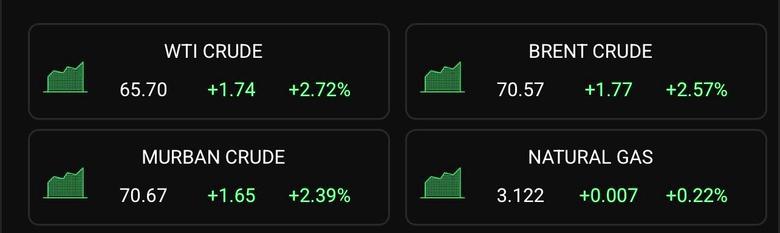
Oil Markets has had its boat rocking.With prices remaining on edge in response to the US-Iran situation,ICE BRENT playing Bullish notes this week towards the $70/bbl & WTI CrudeOil trading at $65/bbl after the failed Oman talks that started off this month guidance being a reduction of activities from US flagged ships on Iranian waters.This is the devils advocate on rising US inventories.Bullish biasness would be conclusive at the $66.33/bbl.Tides of success may lift your boat, but don't forget to oil the rusty hinges.
OPEC+ production dipped in January to 42.56 million b/d, a decline of 270,000 b/d compared to December levels and the first monthly drop in 13 months,driven by output cuts in Kazakhstan, Russia, Nigeria and Libya.This has dealt a blow on the oversupply narrative that's been suppressing prices and we wait on the domino effect in the coming days.
On the US Payrolls Data,Payroll gains for 2025 have been revised down to +181k. Looking into the full history of payroll data, the only year that has been weaker when it comes to gains is 2003.
Value-to-Growth rotation showed more staying power yesterday, as S&P 500 Value held flat while Growth (-0.6%), pushing YTD performance differential to 5.6%; trend most pronounced in large caps, but Value is outperforming across entire market-cap spectrum.
Proof is in the pudding,may we have the appetite for risk as the year has a buffet lined up for us.
Remember, Costs are not there to be calculated, Costs are there to be reduced.
Many blessings from the desk,
Andy Warr,
TophatFinanceGroup.
-----
Earlier:

2026, February, 10, 13:30:00
OIL PRICE: BRENT NEAR $69, WTI ABOVE $64
Brent were down 16 cents, or 0.23%, at $68.88, WTI fell 20 cents, or 0.31%, to $64.16.

2026, February, 5, 08:00:00
OIL PRICE: BRENT NEAR $68, WTI ABOVE $64
Brent fell $1.44, or 2.07%, to $68.02, WTI fell $1.34 cents, or also 2.06%, to trade at $63.80.

2025, December, 2, 19:35:00
OPEC+ WILL SUSPEND
The eight participating countries reiterated that the 1.65 million barrels per day may be returned in part or in full subject to evolving market conditions and in a gradual manner.

2025, October, 14, 07:00:00
OIL PRICE: BRENT ABOVE $63, WTI NEAR $60
Brent rose 22 cents, or 0.4%, to $63.54 a barrel , WTI was at $59.71 a barrel, up 22 cents, or 0.4%.

2025, October, 10, 06:50:00
OIL PRICES WILL DOWN TO $52
The EIA said in a statement that it expects oil production growth to be led by countries outside of OPEC+. Production in South America has been the leading source of growth as new offshore vessels have started up ahead of schedule in Brazil and Guyana this year, the outlook said.

2025, October, 8, 06:50:00
OPEC+ PRODUCTION ADJUSTMENT 137 TBD
In view of a steady global economic outlook and current healthy market fundamentals, as reflected in the low oil inventories, the eight participating countries decided to implement a production adjustment of 137 thousand barrels per day from the 1.65 million barrels per day additional voluntary adjustments announced in April 2023.

2025, October, 3, 06:50:00
OPEC + OVERALL CONFORMITY
The Committee also reaffirmed that it will continue to monitor adherence to the production adjustments decided upon at the 38th OPEC and non-OPEC Ministerial Meeting (ONOMM) held on 5 December 2024, and the additional voluntary production adjustments announced by some participating OPEC and non-OPEC countries as agreed upon in the 52nd JMMC held on 1 February 2024.

2025, August, 21, 06:50:00
RUSSIA'S OIL EXPORTS UP BY 7%
Physical export volumes in July increased 1.4% month-on-month to 7.3 million barrels per day, matching the export volume from a year earlier.